


We live in a motivated world at all times;
USDJPY lower may be motivated by the US Treasury’s desire for a stronger yen, while long-term gold buying is motivated by the debasement of the very currency used to buy and acquire that gold.
Over a long enough horizon:
- S&P 500 buyers are motivated by structural 401(k) bids
- Government bond buyers are motivated by pension fund obligations
Every asset, on every time horizon, has a dominant motivation one that sometimes collides with others, and sometimes moves in harmony.
What’s your motivation to trade the markets? To turn a profit? After all, it says so on the tin.
But many traders, speculators, and investors get blinded by their motivation to assert a view, a belonging, and most fatally — ego attachment.
Left unchecked, motivation can be manipulated into being anything but profit-seeking.
In the case of the issuer of US bonds, led by Scott Bessent, the motivation is to drive lower yields. That view may be held by the Treasury, but prices are set by the markets… or are they?
Throughout the history of sovereign bond issuers, there have been many bouts of artificially influencing the behaviour and range of motion of bond yields: forcing on markets the supply of short-duration or long-duration bonds, often successfully, in an attempt to control yields.
This lowers the burden on the government to service its own debt. But if the yield is artificially suppressed rather than set by market forces doesn’t that imply the risk isn’t being priced accurately?
If the yield fails to compensate for loss of purchasing power and diminished real returns, then it’s no longer risk-free. In any meaningful sense, it loses its value as a safe haven.
So what use does the individual investor have for bonds with a fixed yield and no real risk cushion? Participants would be hard-pressed to own assets that lose them money in an environment that devours purchasing power day by day.
Shelve that thought for a moment.
What if cash flow–rich companies issue bonds of similar quality at a higher, market-set yield one that actually reflects investor compensation? The pendulum would swing from public debt to private debt, simply because private debt pays better.
If Treasury succeeds in suppressing the yield on public debt below the return investors can obtain elsewhere for comparable risk, the battle for capital moves elsewhere.
If you know why someone does something, you can predict what they will do next. Treasury wants lower yields but yields rise anyway. what happens next? We don’t have an answer to that question but we have a date.
During the next QRA meeting where Treasury sets its intended borrowing needs Bessent will be confronted with a shortfall north of $1.4 trillion for FY 2027/28, and the runway for increasing the burden on short-duration borrowing has all but run out.
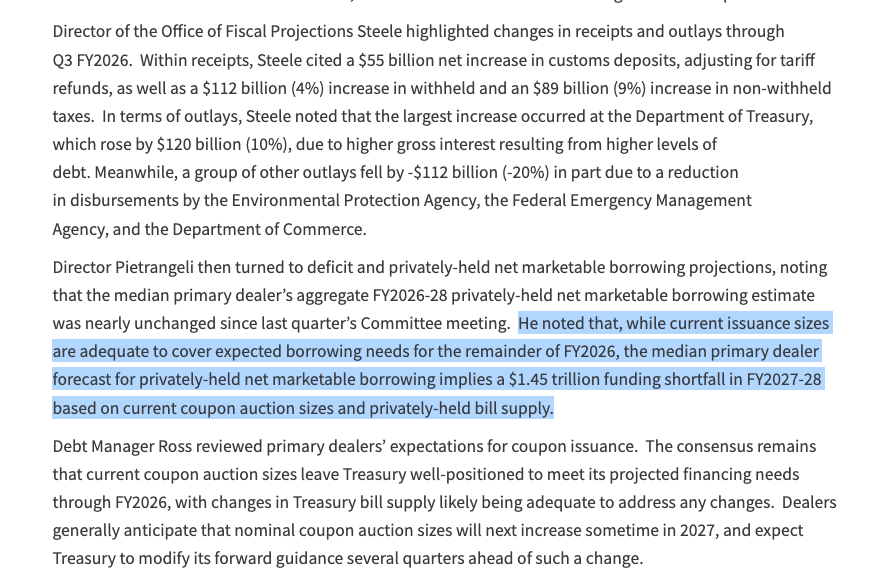
“The latest TBAC analysis points toward a future need to increase coupon issuance. Under current auction sizes and bill supply, primary dealers see a $1.45 trillion funding shortfall emerging across FY2027–28.”
TBAC’s recommendation is to start adding duration and reduce the burden on short-term borrowing. That shift to short maturity made during the October/November 2023 QRA has helped give risk markets a boost. During the Q3 2023 stress, market feared increased duration supply. Treasury delivered duration supply, but less than feared and bonds rallied,equities rallied - yields fell.
Bill heavy issuance in 2023 was absorbed largely by draining the ~$2T reverse-repo stock, so it was close to liquidity-neutral. If that buffer is now largely depleted, bills no longer cushion the way they did.
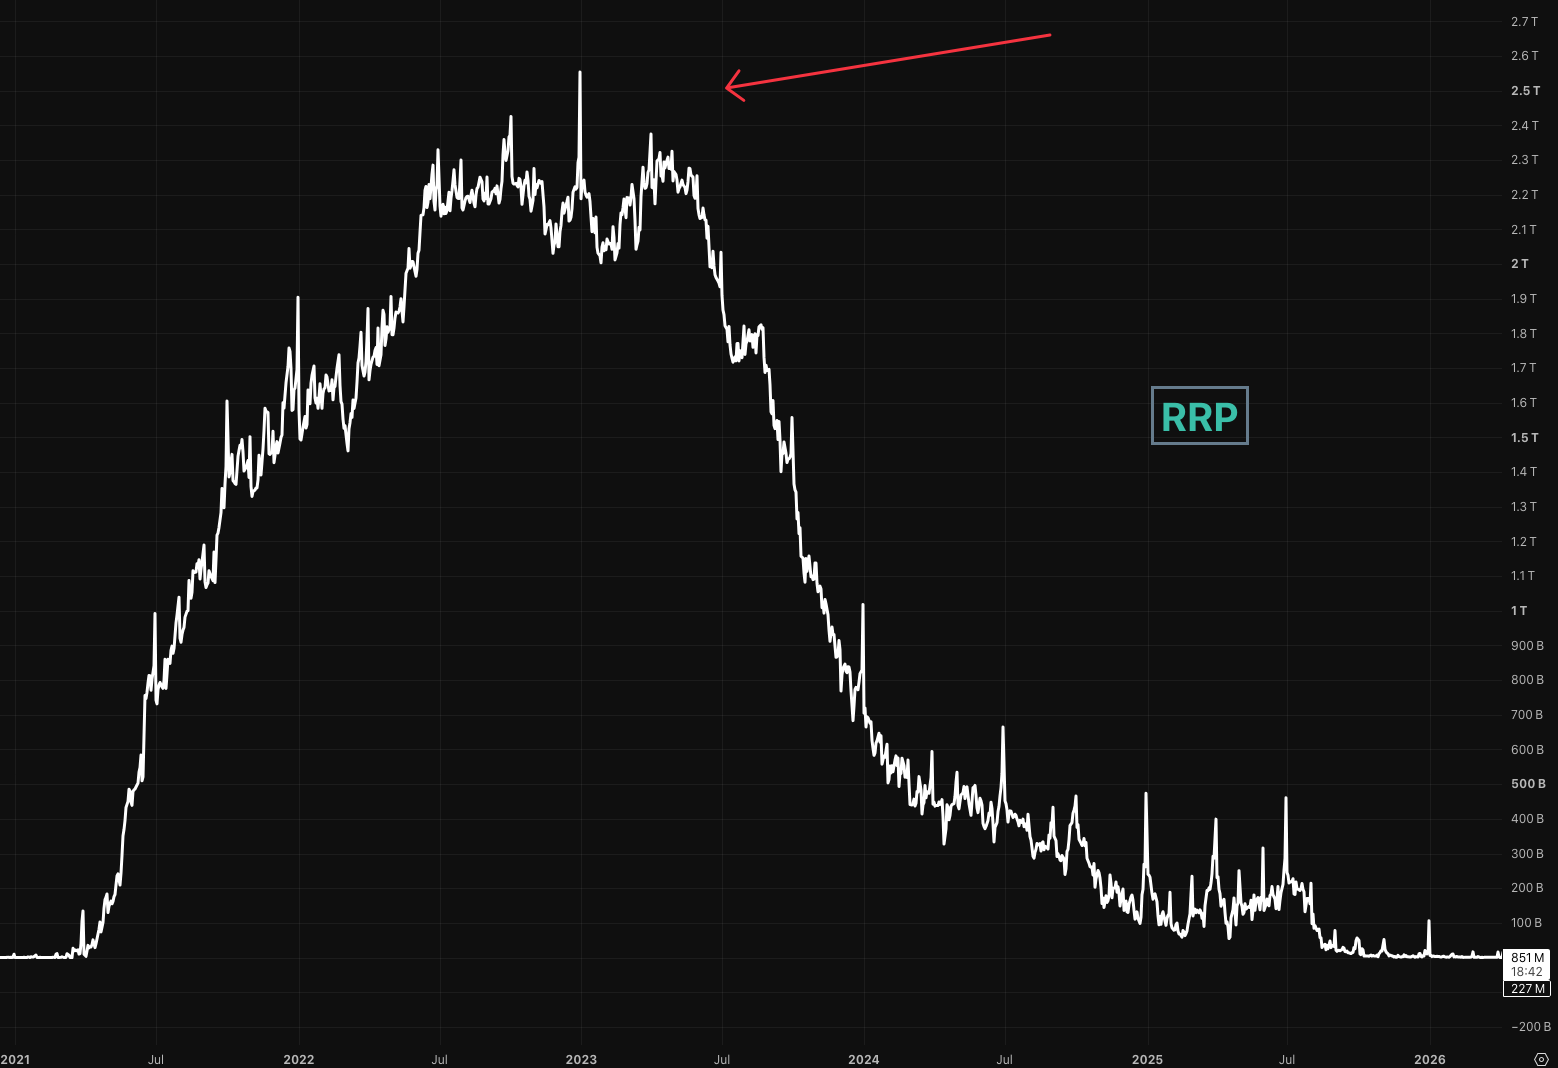
Reversing that accommodation will have reverberations across risk assets such as the S&P 500. Yet risk assets have not priced in, or adjusted to, that outcome. At the time of writing, we are less than 1% from all-time highs.
The 10-year yield, on the other hand, has risen considerably — potentially reflecting expectations for a change in borrowing composition at the November 2 QRA. This is interesting. If it materialises, “buy the rumour, sell the fact” could translate into buying back bonds at levels consistent with the new supply.
In a way, the market is saying to the government: if you’re going to increase long duration, we want to make sure you do so at the worst possible price. The asset rotation will see liquidity withdraw from yield seekers into bonds. To borrow the phrase gentlemen will prefer bonds.
There are numerous ways to calculate a US 10 year yield that accurately reflects the supply storm. And this offers a range of outcomes:
Low case (stock-effect only): ~5.1-5.2%
Central case (my best guess): ~5.7-5.8%
High case (full deficit-signal weight, or a 2023-style abrupt catch-up): ~6.0-6.2%
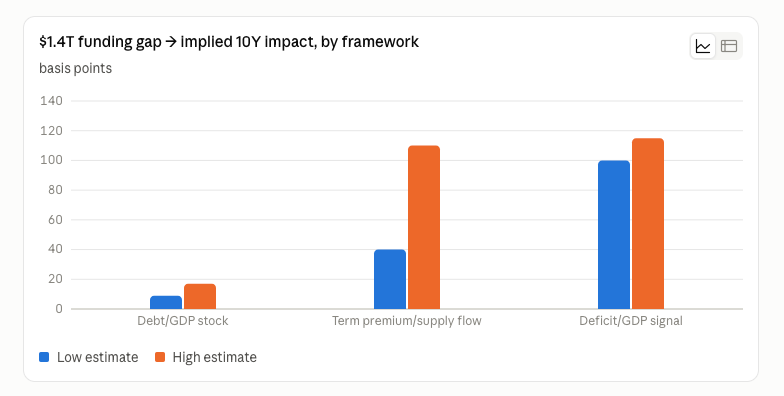
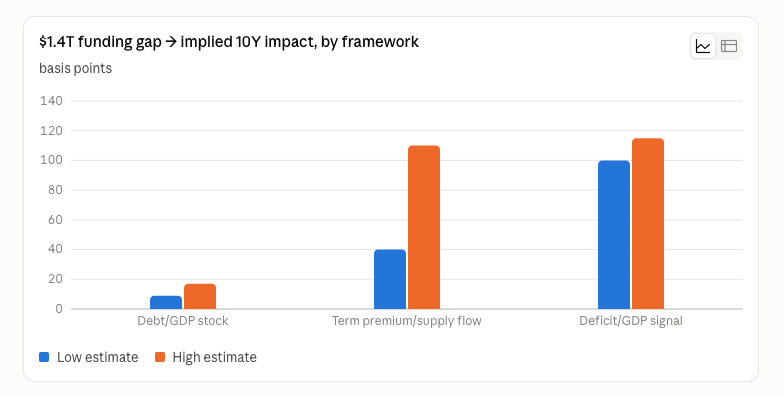
A realistic incremental from this specific gap being closed with duration is more like +25 to +35 from here. However if they keep coupon issuance (10y) the same, the 10y can fake a calm until a failed coupon auction then you get the 50–75 bps anyway, just later and messier.
Bessent’s job is to fund a large deficit without letting the long end blow up. The tool so far has been bills: cheap, short, and easy to roll. When coupon sizes stay frozen and privately-held borrowing keeps rising, the gap shows up as either more bills or more duration. TBAC already priced the second option: a $1.45 trillion hole in FY27–28 at current auction sizes.
The bond market has a clear understanding of Bessent’s motivation but he has a poor track record of asserting that ‘ will ‘, causing turmoil in his wake . And when uncertainty is dominant, the investor community is left with their imagination closing the uncertainty gap, and more often than not prices will reflect their angst. Thus expectations of yields climbing higher in a worst case scenario gives us a tradable roadmap.
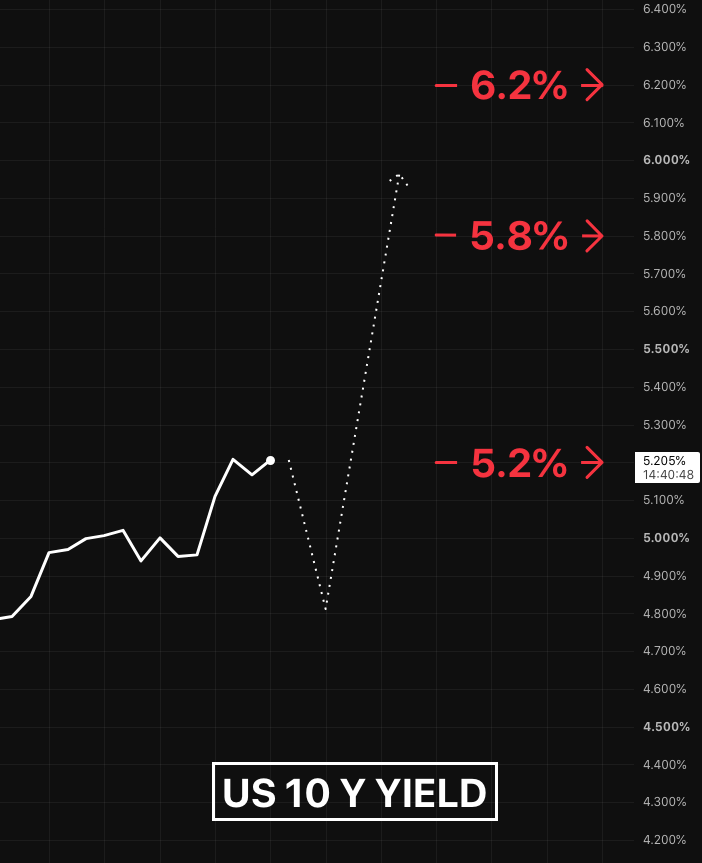
While the canny move by the Treasury will, ultimately in our view, be to increase short-term debt supply and alleviate duration funding pressure (very risk positive for assets), the interim path crossing the pain threshold , is clearly gathering momentum.
Once peak yields come into view, capital rotation from equities to bonds can dampen stocks and even unravel this year’s rally. We have a window for this scenario to prove itself: it likely peaks during the week commencing October 26th, ahead of the QRA.
Our central case is that medium-term bonds bottom (yields top) as equities top. The driver is fear of an avalanche of duration supply and front-running by the bond trading community ahead of the November date.
Equities have not marked this. The 10-year has. If the market spends the next four weeks front-running a duration dump into November, the sequence is:
-One more high in stocks while yields are still “only” mid-5s
-Then a liquidity pull as cash rotates into the cheapening long end
That is a 5–12% air pocket, not a new bear market.
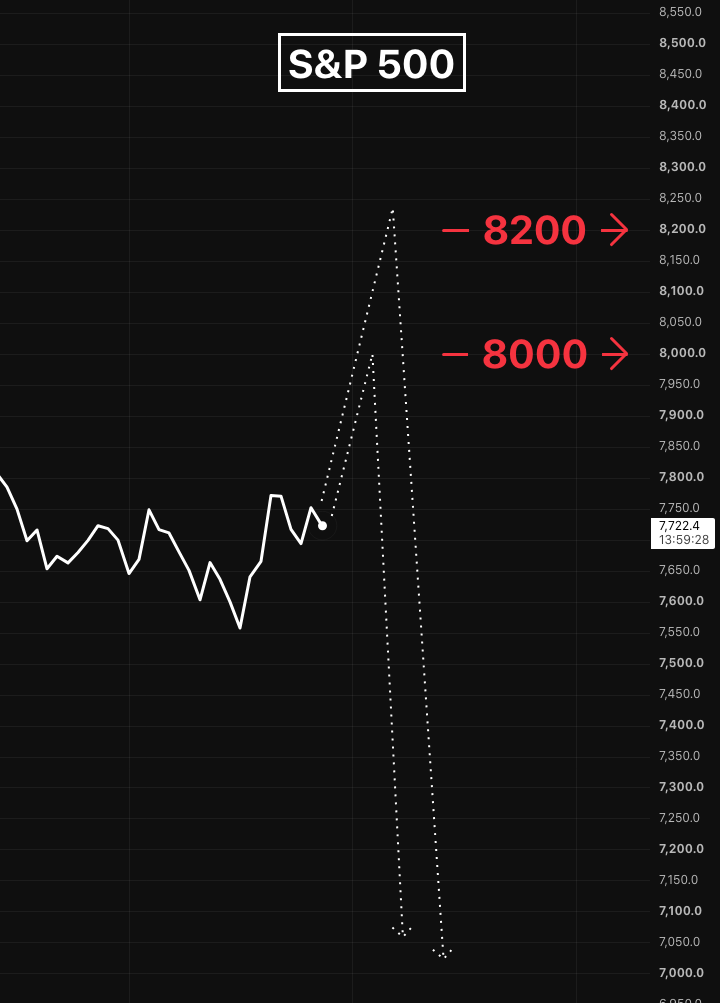
The scenario above points to a flat-to-negative year-over-year close for the S&P 500.
However, it is not lost on us that shorting the secular S&P 500 bull market has historically low odds. As a matter of fact we can see a new all time high around the corner. What we are saying is this:
If the 2022-2023 bear market was snuffed out by swapping duration bonds for short term bills. Then turning the valve the other way should cut of those flows. However the third order thinker among you is already asking:
“What happens because of what happens next, and then what happens because of that?”
In other words, if markets turn down and the S&P 500 closes flat to negative YoY, per analysis above and reasoning, then: What is the smartest move from here?
For us, the downturn will be an excellent opportunity to open our wallets and bet on risk.
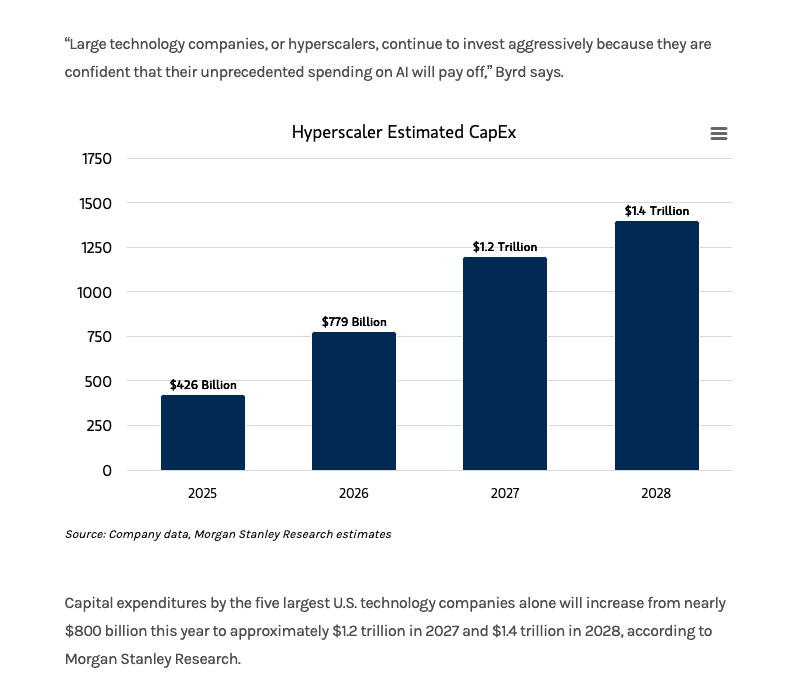
Because when everything is cheap while hyperscalers are outspending the Department of Defense of the USA, then cash is the risk.
That is correct: the hyperscaler CapEx is expected to surpass what the United States spends on the military for the financial year 2027.
We want to be loaded at the lows when the time comes. And following a very successful tool that has produced outstanding bottom-catching signals across all regimes and has given risk seekers the chance to go in during calculated down turns.
We are anxiously waiting for the pieces of the puzzle to fall into place. So we can use this tool again. We were able to step in and buy dips with increased confidence as the S&P 500 (blue line) has reacted positively every single time:
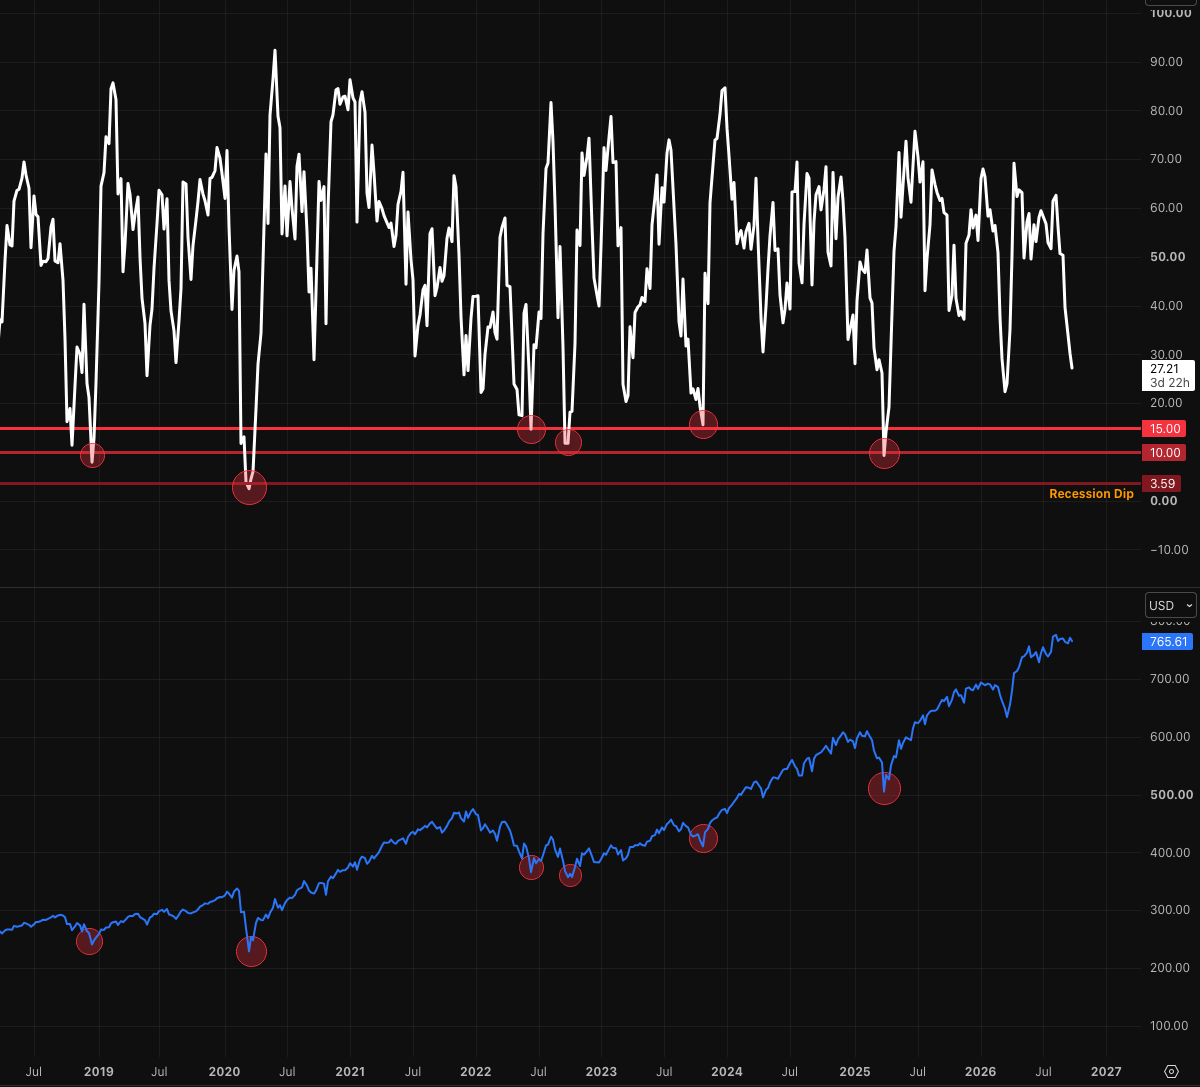
We are highly motivated to single out extreme scenarios, where the market gets exposed to the risk of one sided moves. Producing an opening to bottom catch a secular bull.
The trade is not “short the secular bull.” The trade is: don’t be the one holding the bag into the QRA, and be willing to buy the dip if they blink and stuff the gap back into bills.
We have a dip framework that has marked the last several risk on entries. The framework is only the trigger for when the dip comes.
Trade Strong
Miad
*The Charts and Analysis was originally shared on our private discord group accessible here: SPECULATORS TRADING CHANNEL
**THIS IS NOT FINANCIAL ADVICE, YOU MAY LOSE ALL YOUR MONEY FOLLOWING THE ANALYSIS ABOVE. THERE ARE NO GUARANTEES IN TRADING. THE RISK IS REAL.